When the Wind Drops: A Homeowner's Guide to the First 24 Hours of Storm Damage
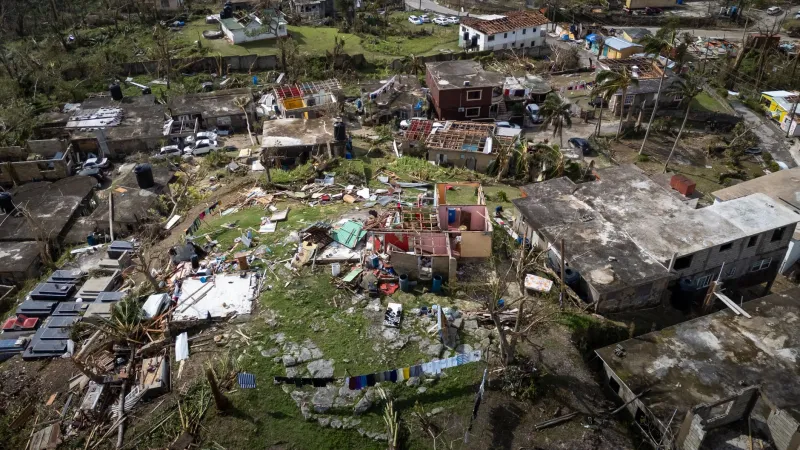
A named storm crossing the British Isles can lift a run of tiles, flatten a fence and force rainwater through a ceiling in the space of a single afternoon. What happens in the twenty-four hours that follow tends to determine how quickly the property is made watertight, how smoothly an insurance claim progresses, and whether the same repair ends up being paid for twice.
The guidance below is deliberately narrow. It deals with the first day, not the first month. It separates work that genuinely cannot wait from work that comfortably can, and it explains why the order in which you do things matters as much as the things themselves.
Before any tidying begins: is the property safe?
Garden debris can wait. Personal safety cannot. Work through these checks before you touch anything:
- Structure. Sagging ceilings, a bulging wall, a cracked chimney stack or a lintel that has shifted are all reasons to stay out of the affected room and call a structural engineer or your local authority building control team. Water-stained plasterboard that is holding its weight can usually wait for an inspection.
- Electricity. If water has reached sockets, the consumer unit or any fixed appliance, isolate the supply at the main switch only if you can do so without touching wet surfaces. Do not repeatedly reset a trip that keeps tripping — that is a fault looking for an electrician.
- Gas. Any smell of gas means leaving the property and calling the National Gas Emergency Service on 0800 111 999. Do not operate light switches on the way out.
- Power cuts. In England, Scotland and Wales, report and track outages on 105. Avoid candles; torches and battery lanterns are the safer choice, particularly in homes with children or pets.
- Floodwater. Standing water outdoors after a storm is rarely clean. Gloves and wellingtons are sensible, hands should be washed after contact, and children and pets should be kept away from it entirely.
Make-safe work is not the same as a repair
Insurers generally expect policyholders to take reasonable steps to prevent further damage, and most policies will meet the cost of that emergency work. What they do not expect is a permanent repair carried out before anyone has had a chance to look at the damage.
Typical make-safe measures include sheeting a damaged roof using existing fixing points, boarding a broken window, bracing a gate or door that will not secure, isolating the water supply where pipework has been disturbed, and moving furniture and valuables clear of a leak. Roof work is not a do-it-yourself task at any height, and a fall from a ladder is a far worse outcome than a wet ceiling.
Keep every receipt. If you appoint a contractor for emergency work, ask for a written description of what was done and photograph it afterwards.
Photograph before you clear up
Evidence is easiest to gather in the first hours, while the damage is still visible and before the clean-up begins. A sensible sequence is:
- A wide shot of each affected room or elevation, showing context.
- Close-up images of the specific damage.
- A short narrated video walkthrough, moving slowly and naming each room.
- Photographs of damaged belongings before anything is discarded, together with approximate age and value.
Do not dispose of damaged items until your insurer or loss adjuster has confirmed that it is acceptable to do so. Where storage is impractical, photograph thoroughly and keep a written list.
Notifying the insurer on day one
Call your insurer's emergency helpline on the day of the damage, even if the full extent is not yet clear. Have your policy number to hand, note the claim reference, and ask three specific questions: whether they operate an approved contractor network, when a loss adjuster is likely to attend, and whether you may appoint your own local firm for permanent repairs.
It is also worth asking what the policy says about alternative accommodation, since a property that cannot be heated or made secure may not be habitable. Record the name of everyone you speak to and the time of the call.
Doorstep callers and unsolicited offers
Storms bring out both genuine local firms and people who see an opportunity. A company that knocks uninvited within hours of a weather event deserves polite caution rather than immediate trust. Before appointing anyone, check the company number at Companies House, ask for proof of public liability insurance, confirm any trade body membership and what it actually covers, and insist on a written quotation that separates make-safe work from permanent repair.
Be wary of large cash deposits, of pressure to sign on the day, and of any suggestion that you must use a particular claims management company to progress your claim. You do not. Our own guidance on vetting repair firms applies just as firmly the morning after a storm as it does in a quiet week in June.
What can genuinely wait
Once the property is secure and dry, a considerable amount can be deferred without risk: blown fence panels that are not a security concern, a section of gutter, garden furniture, cosmetic paintwork, non-urgent repointing and the assessment of damp staining on an internal wall where the leak has been stopped. Photograph these items now and schedule them for a proper quotation later.
What cannot wait is anything involving structural movement, water tracking towards electrics, an unsealed roof, or a leak that will worsen with the next rainfall.
Start the record now, not later
Open a document or a folder today. Note the date and the weather event, what happened, who you called, the reference numbers, the costs incurred and where the photographs are stored. That single page will serve you when the assessor arrives, when a warranty claim arises in three years, and when a buyer's solicitor asks what has been done to the property. The 2026 storm season will pass; the paperwork is worth keeping.